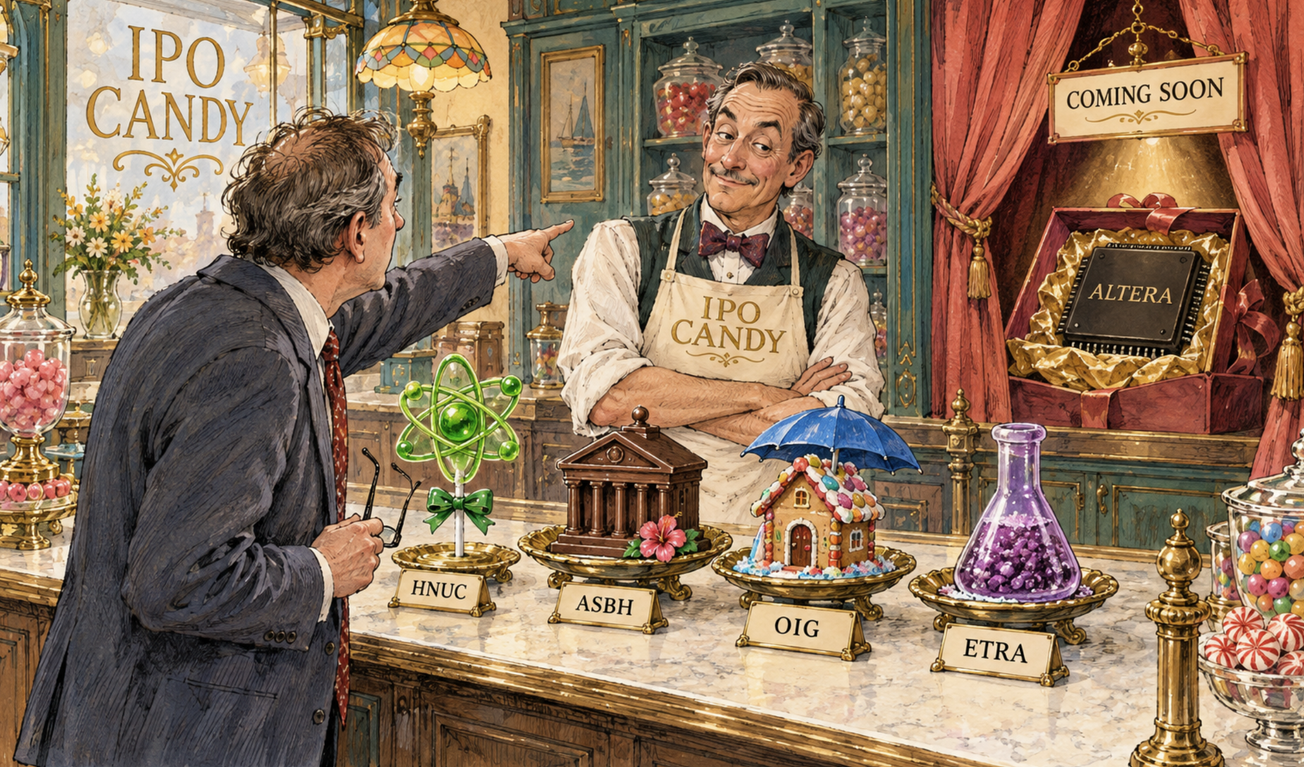
This week we have four deals on tap and more in marketing for next week. Also of note is Altera which has reportedly confidentially filed for their spinoff IPO. There's a bit more on that one below the fold.
Here's the rundown for this Thursday/Friday:
Holtec Nuclear Corp $HNUC is tapping into an improving market for nuclear thanks to regulatory reform, government incentives and increasingly high oil and fuel prices. It's a bit of an odd duck from a positioning standpoint. The company was founded back in 1986 and Dr. Krishna Singh is on a mission. They have a strong services business which lowers the risk in terms of new nuclear adoption but they have irons in that fire too with their SMR 300. I find the whole space very crowded but we have the nuclear candy tracker so will be adding this one to it.
American Savings Bank of Hawaii $ASBH already priced at $16 with the books closed. It should open for trading today. This is a good little "growth bank" that has cleaned up their loan portfolio and aims to grow interest margin and pay a healthy dividend. Based on P/B it would have to trade down to $13-14 for me to be at all interested.
Orion180 Insurance Group $OIG is a tech-forward specialty P&C operating in the housing markets of California, Texas and Florida. I am impressed with this company and was a bit surprised that the book is described as "price sensitive" and may have to price at the bottom of the $15 - $17 range. This is one to do more work on post-IPO before the quiet period is over.
Electra Therapeutics $ETRA is expected in the $14-16 range and should trade Friday. To my simple mind this is a pretty conventional monoclonal therapy biotech in Phase 2/3 so not of interest like Scribe Therapeutics a few weeks ago. $SCTX.
Altera Returns
Altera is a significant semiconductor company in the FPGA space with ~$1.6B in revenue. It's owned by Intel $INTC and Silver Lake so we don't have a bead on financials. The plan is for a $2B deal at a $9B valuation but as we saw with Mobileye $MBLY it might be a lot smaller.
Why investors will care:
- This is a genuine large scale FPGA asset, not a story stock. They were one of two companies dominating the space when Intel acquired the company in 2015.
- As a standalone company they may be able to reverse perceptions and market share losses from being "slow" and underfunding R&D.
- They have real AI exposure but it is indirect via surrounding components and connectivity. They have some potential strengths at the edge for vision, robotics, sensor fusion and automation.
- A rising tide lifts all boats.
We will be parsing more when the filing is live and we can see more. Plan to get smarter on AMD/Xilinx, Lattice Semiconductor and for small cap investors QuickLogic.